Below is a review of the posts on Facebook and LinkedIn from the past week. You can check out the full posts by clicking on the links.
NOTE: remember that we now post every other day.
The posts on Monday 10/26/2026, here and here, reaffirmed that tighter condo financing rules add new hurdles for buyers and sellers. Know how this affects you in either role.
Unless your head has been (deep) in the sand, you know that the residential condominium market has experienced considerable challenges recently, and forthcoming regulatory modifications (some effective now, others to take effect early 2027) are anticipated to introduce additional complexities to the purchase/sale process.
Fannie Mae and Freddie Mac are implementing more stringent underwriting criteria for condominium financing. Who they are, and their share of the mortgage loan market, is in the post. The expedited review procedures that previously allowed highly qualified purchasers to obtain mortgage approval after a superficial assessment of the financial and structural conditions of condo properties are now discontinued, replaced by comprehensive evaluations applicable to all but the most modest residential condominium buildings.
And in January 2027, the other layer kicks in: Fannie Mae and Freddie Mac will mandate that condominium associations maintain a minimum reserve allocation of 15% of their assessment revenue, an increase from the current 10% requirement.
Why did Fannie and Freddie make these changes? If you don’t already know form various news articles and even some of our most recent prior posts, Sun. August 9, 2026, here and here, Mon. August 3, 2026, here and here, Thursday May 21, 2026, here and here, and Friday April 3, 2026, here and here, then see this post. So even though the changes are well-intentioned, they represent an additional impediment within a marketplace already characterized by declining valuations, expanding inventory levels, and heightened purchaser apprehension regarding special assessments and recurring monthly obligations. How one mortgage banker summed up the situation is in the post.
Market Challenges, Performance & More
Condos have traditionally underperformed relative to the single-family residential market, exhibiting price declines that occur more rapidly and recoveries that progress more slowly due to their comparatively limited purchaser pool. The disparity has intensified substantially in recent years based in large part on the things described in the post.
Further contributing to the issue is that numerous condo associations have been forced to implement substantial increases in monthly assessments – or impose significant special assessments – to achieve compliance with state mandates concerning deferred maintenance obligations and reserve funding requirements. The effect of all of this is that condo values have declined 2% from their peak levels several years prior, according to Zillow analytics. In some areas around the country it is worse – see the post.
The continued subdued purchaser interest does not help either. Condo transactions declined 2.7% in August relative to the preceding year, based on National Association of Realtors statistics. How that compared to single-family home transactions is noted in the post. The national numbers for inventory duration (the time frame required to liquidate all available inventory at prevailing transaction volumes) for both condominiums and single-family homes are also in the post and further support the condo market conundrum.
Fannie Mae and Freddie Mac maintain comprehensive criteria for the acquisition of condo loans. Setting aside (for the moment) the recent regulatory modifications, various other considerations, including those listed in the post, may result in a property (i.e., the condo building or community) being deemed “non-warrantable,” the import of which is in the post.
While non-warrantable condominiums may be listed for sale without limitations, the prospective buyer base shrinks because prospective purchasers lacking eligibility for Fannie Mae and Freddie Mac mortgage products must either provide full payment in cash or pursue alternative financing options that typically carry elevated interest rates. And under those circumstances, a large portion of those potential buyers just decide not to purchase.
What helps both condo purchasers and sellers in this new market? Having and understanding the required association documents and information.
TAKEAWAY: Condo associations have been grappling with the new Fannie and Freddie regulatory changes for a few months now and will continue to do so in the new required reserve environment in and after January 2027. Consult a community association lawyer if you have questions or need assistance.
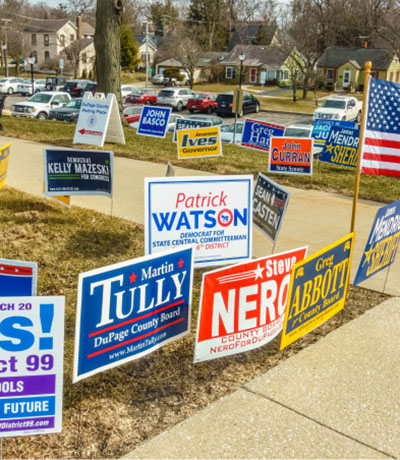
The posts on Wednesday 10/28/2026, here and here, talked about signs of the times: political signs, flags, and community associations. You absolutely must know what your condo or homeowners’ association allows before putting out any signs this election season.
The Foundation for Community Association Research’s 2026 homeowner satisfaction survey (linked in the post and a useful resource) reports that 88% of residents vote in national elections, 83% in state and local elections, and nearly seven in 10 (69%) vote in their community association board elections. That’s great, right?!?
In most states, within the next few days or weeks voters will elect all 435 seats in the House of Representatives and 35 seats in the Senate. Also this year, voters in 39 states will elect governors, with 18 governors running for reelection and 21 open seats due to term limits or retirements. That’s a lot of possible change. Given the stakes, signs and flags are more relevant than ever considering community association residents’ strong track record of civic engagement combined with the sheer volume of ballot content and political signage.
Conversations about political signs and flags in community associations focus on display and content and can come up often. Boards, managers, and residents must be educated on applicable laws and their governing documents to ensure that all flags and signs are acceptable.
Everywhere one looks these days, there is a finger pointing to the First Amendment and its protections. What the First Amendment guarantees is in the post. But the First Amendment does not apply to private organizations like community associations which can adopt and enforce reasonable restrictions regulating political and noncommercial speech within the community. And some states have broad statutory free-speech rights that does not depend on the status of the actor (as does the First Amendment).
CAI’s Public Policy Recommendation (linked in the post) recognizes and supports the rights of residential community associations to regulate political and noncommercial signs within those communities consistent with federal, state, and local laws. The type of legislation supported by CAI is described in the post. Because every community is unique, legislation should allow an association to develop reasonable rules and regulations concerning the time, location, materials, size, number, and manner of where political and noncommercial signs, displays, or activities are located while preserving residents’ freedom of political expression.
State laws and Association rules matter too. These vary (pretty widely). Currently, 28 states have laws regarding political flags and signage. And even if there is no state law, the association’s governing documents may have restrictions, so best practice on how to proceed is in the post.
CAI supports legally sound, fair, and equitable political sign rules and uniform enforcement procedures in community associations. CAI has resources (linked in the post) to help associations effectively manage sign and flag rules and regulations (and check on existing state legislation).
Communities may adopt individual rules to reflect the needs and desires of residents. Managers and boards should send approved rules by email, upload notices on the community website or social media page(s) and plainly display them to encourage compliance and transparency. One of the most important pieces of any political sign/flag policy is noted in the post.
TAKEAWAY: Community associations have the right to place limits on political signs/flags, but it is best to discuss them with a community association lawyer before implementation to ensure they are reasonable and legally compliant.
The posts on Friday 10/30/2026, here and here, told us about the biggest mistakes people make in their wills. Pay attention and learn grasshopper.
Your last will and testament is one of the most important legal documents that you will ever make. It allows you to direct where you want your property, guardianship and debts to go after you die, and it allows you to appoint an executor to ensure your directions are carried out. But so many Americans don’t have a will right now (two out of three adults according to the 2025 survey linked in the post). Nd that’s despite the pandemic! The top reasons people gave for not having a will are in the post (and probably will not surprise you). Not having a will can be really detrimental after your death. But beyond that, here are the biggest mistakes estate planning attorneys see clients make.
1. Assigning co-executors. Bad bad bad. You can havealternate/successor executors, but not co-executors. When people are preparing their wills, many think that, in fairness, they want to make all of their children co-executors. Bad bad bad idea. What happens if they don’t agree on something? Real-life examples are in the post.
And those disagreements often require that each co-executor engage their own attorney, so now it starts to get costly. How one attorney solved the issue is detailed in the post (and makes sense). Another attorney suggested how co-executors might be handles if you insist on it – again, see the post, but make sure the will is clear and specific.
2. You believe that a will is all you need to avoid loved ones going to court. Since this is on the list, you know that is not correct. The mere existence of a will does not mean the estate will avoid probate (which process is described generally in the post). Although a valid will can ultimately direct where certain assets are allocated, it will likely not avoid probate if some assets are titled solely in your name. A real-lief example of why this is a mistake – and how much extra it cost – is in the post.
3. You’re too vague about items with sentimental value. “Be specific. Don’t leave it up to the beneficiaries (or executor) to sort out. You may see them all getting along now, while you are alive, but that may well change after your death. Money (and things) changes people when the gatekeeper is not there. Yep, a real-life example is in the post (and you may know of one or more situations like this that happened to you or someone you know).
What may surprise you is that it’s not always money, but the sentiment behind something that is valued. Why that hits is in the post. So just be specific and avoid the headaches for everyone down the road.
4. You don’t update your will to reflect life changes. Because life happens. To everyone. Whether or not you want it to.For better or worse. Andcertain life events require the documents to be updated, such as those listed in the post. It’s recommended that your estate planning documents be reviewed periodically, but at least every five to seven years.
Ne common thing that occurs when documents are not updated is described in the post. Don’t let that happen to you.
5. You don’t think through whether the gift you leave someone will actually help them at the time of your passing.
Ok, we know that Mistake #1 is not having a will (or other documents) in place. But that’s not the end of it – you must also think about the effect of the documents on the beneficiaries. What you think is a wonderful gift might not end up being so after your death. Amounts, beneficiary age (at either end of the spectrum), and other things discussed in the post are to be considered for the reasons also detailed in the post.
6. You don’t leave instructions about where to find your will. How can it be implemented if it can’t be located? The original is almost always required in order that the executor can begin probate (or otherwise act). A good estate planning attorney will tell their clients the things noted in the post so this won’t become an issue in the future.
7. You don’t work with someone who actually understands estate law. Every attorney does not know or practice in every area of the law. And estate planning documents are legal documents with legal implications, now and in the future. Don’t just go to a friend or relative (or their friend or relative) because they are a lawyer. What can happen when you don’t end up with the right documents for your situation (which differs from every other person’s situation), bad things can happen. Such as those noted in the post.
TAKEAWAY: Learn from other’s mistakes – DON’T do the things in this post. But DO work with an estate planning lawyer to review existing or put in place new estate planning documents that are right for your situation.