Below is a review of the posts on Facebook and LinkedIn from the past week. You can check out the full posts by clicking on the links.
NOTE: remember that we now post every other day.
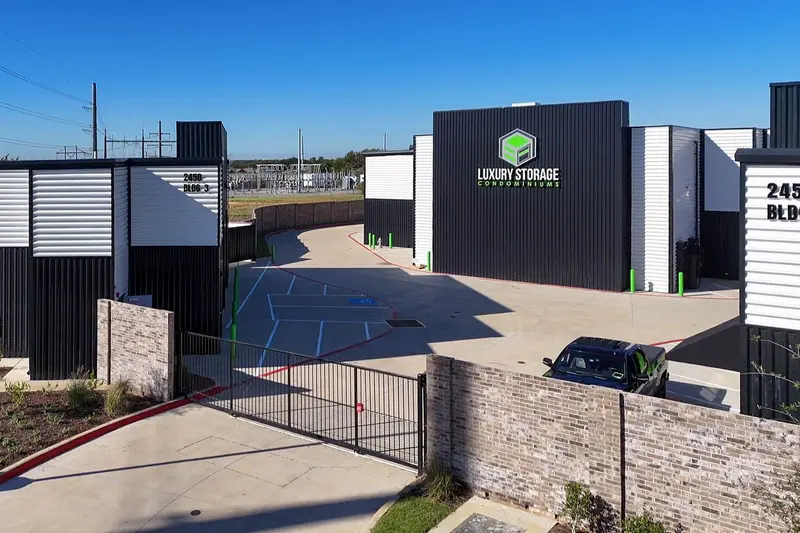
The posts on Monday 11/09/2026, here and here, told us about new Yoga in new luxury storage condominiums? This could be an interesting mix of uses – read to see why.
The details. The new condominiums will offer customizable, secure and spacious options, according to the website. The commercial marketing and operations director said they noticed there wasn’t anything quite like this in the local market and felt it would be a great addition to the community.
Here’s the interesting part: for owners hoping to use the space as a studio or quiet retreat (not just storage), they can incorporate air conditioning and soundproofing. And of course the condominiums can also be used for boats, vehicle storage, as a fitness or gaming den or to showcase and store valuable collections. Some of the build-out packages that are available might surprise you with what they contain (given the potential mixture of uses). See the post for more on that. And the property is fully fenced with gated access for owners.
Looking ahead. The price range is listed in the post and depends on size. Construction is underway. How is the flexible concept going over? See the post.
TAKEAWAY: Get that idea of condominiums being solely residential out of your head – they could easily be solely commercial or mixed-use.

The posts on Wednesday 11/11/2026, here and here, suggested you take a page out of Sam Walton’s playbook for your estate planning – but consult an estate planning attorney on tax implications.
Sam Walton gifted 80% of his retail business in 1953 at near-zero value, letting hundreds of billions grow tax-free outside his taxable estate. How did this work out for his heirs? And is a similar move good for you?
If you own a small business, a rental property, or a chunk of stock you expect to increase in value, the Walton family already ran the playbook. In 1953, Sam Walton and his wife Helen took advice from her father and organized their retail holdings as a family partnership. They handed roughly 80% of that business to their four children, Rob, John, Jim, and Alice, each receiving a 20% stake, nearly a decade before the first Walmart (NYSE:WMT) store opened its doors in Rogers, Arkansas on July 2, 1962. That single (dare we say simple) decision – gifting an asset while it was worth almost nothing – is why the heirs have avoided a catastrophic federal estate tax bill despite a combined family fortune tracked by one index at more than $450 billion in 2026. This strategy is still allowed by the tax code today and you do not need a retail empire to use it. Let’s take a deeper dive to see if it might be right for you.
The Buried Rule: Gifts Are Frozen at Today’s Value. The key quirk in the federal estate and gift tax code is straightforward once you see it. When you give away an asset during your lifetime, the IRS values that gift on the day you make it. Why does that matter? Because every dollar of appreciation after that date happens while in someone else’s hands, entirely outside your taxable estate. What Sam Walton did followed the tax code. And all the growth that followed – the stores, the split-adjusted shares, the decades of dividends – grew in his children’s names rather than his name (or future estate). In his autobiography “Sam Walton: Made in America,” Walton plainly spelled out the logic. See the post. And that is the principle ordinary families (i.e., the majority not in the Walton stratosphere) miss. The earlier you transfer an appreciating asset, the more future gain escapes the estate tax. The impact on the Waltons is noted in the post.
The Proof in the Code. This play comes directly from the intersection of how the IRS structures gift and estate taxes under Internal Revenue Code Chapter 12 (gift tax) and Chapter 11 (estate tax). The numbers for 2026 are the most favorable in decades. The annual exclusion for gifts stands at $19,000 per recipient, while the One Big Beautiful Bill Act, signed into law on July 4, 2025, permanently raised the estate, gift, and generation-skipping transfer exemption to $15 million per individual, up from $13,990,000 in 2025. Married couples together can shelter $30 million. The OBBA also indexed the figure for inflation starting in 2027, using 2025 as the base year, so the exemption will grow rather than erode over time (which has been a problem with much former and existing legislation). What would have happened without the OBBBA? See the post. The $15 million exemption is both the basic estate exclusion and the lifetime gift exemption. What that means is explained in the post.
Who Can Actually Use This Play. Any U.S. taxpayer who holds an asset likely to appreciate can apply this strategy. It works best for owners of closely held businesses, founders with pre-IPO equity, landlords with rental property in an early-stage market, and parents holding concentrated stock positions. Married couples might benefit even more – see the post. The strategy is less compelling for families whose total estate will be well below $15 million and plan to leave low-basis assets at death. In those cases, the step-up in basis at death often delivers a better outcome (tax-wise at least).
How To Run the Walton Play at a Smaller Scale. You are not Sam Walton, but you can still try to determine if this play might be right for your situation.
- Identify the asset you believe will appreciate the most: private company shares, LLC units in a rental property, or a founder stake.
- Obtain a defensible appraisal at today’s low valuation (i.e., before appreciation and taking into account the various things listed in the post).
- Gift up to $19,000 per recipient per year to stay inside the annual exclusion. Or make a larger gift and file Form 709 to draw down your $15,000,000 lifetime exemption.
- Consider a family limited partnership or trust. The benefit of that is described in the post.
- Let time do the work. Every dollar of future growth belongs to the recipients, not to your taxable estate.
The Catch Nobody Advertises Ah, you knew there had to be something, right? There is one tradeoff worth understanding before following the Walton pay. Lifetime gifts carry over your original cost basis to the recipient. For example, if you paid $10,000 for stock that is now worth $1 million and transfer that stock as a gift, your child inherits your $10,000 basis and will owe capital gains tax on the full appreciation when they sell. How that contrasts with what happens when the child instead inherits the stock from you is in the post. So the decision comes down to estate tax exposure versus capital gains tax exposure. The Walton approach wins decisively when the asset is set to appreciate massively and the family intends to hold it across generations, as the Waltons did with their Walmart shares. But it makes less sense in other situations as identified in the post.
TAKEAWAY: Do the math carefully, preferably with an estate planning attorney or tax professional, before signing any gift or estate planning documents. But definitely look into this to see if it’s right for you.

The posts on Friday 11/13/2026, here and here, were about 55+ Communities: How to Choose an HOA (That Won’t Give You Headaches). All tips here are important to every buyer, but the next to last is key in 55+.
While a typical home listing might tout spacious bedrooms and proximity to schools, the marketing for homes within 55+ communities appeals to prospective residents from a different angle. You’ll see images of friends lounging glamorously by the pool and playing tennis, with enticing words like “resort-style amenities” and “low-maintenance living.”
In addition to attractive lifestyle comforts, buying a home in a 55+ community often means offloading the time-consuming (and physically demanding) upkeep that homes require. You’re also virtually guaranteed that your neighbors will be in a similar stage of life as you. However, shopping for one of these homes is more intensive than just comparing square footage and property taxes. To really make an informed decision that you can feel confident about, you’ll need to compare condominium or homeowners’ associations (here jointly HOAs) too. And yes, that home will almost always be in a community governed by an HOA.
Know the rules and regulations of the community. If you’ve never lived in a neighborhood with an HOA, this may be one of the bigger adjustments you’ll face when you move. While HOAs provide benefits like maintaining communal facilities, landscaping and removing snow, HOAs also set rules, restrictions and expectations for residents. As you explore communities, ask early on to see a copy of the covenants, conditions and restrictions (CC&Rs or Declaration). This document contains the guidelines that all residents have to follow and that the Board will enforce.
Each HOA will have its own regulations, and you don’t want to fall in love with one neighborhood only to learn that the CC&Rs don’t align with your needs and lifestyle. One example (that would matter to some people but not others) is in the post.
And what if you’ve got a green thumb? An HOA might explicitly prohibit you from gardening because the association has authority over every plant in the front and back of your (future) home.
A 2026 survey (noted in the post) found that among baby boomers living with an HOA, 52% reported that their association brought them “no stress” in day-to-day life. The percentages reporting minimal stress” and “moderate” or “frequent” stress are also in the post. But perhaps as important, the survey also reported that 40% of respondents in this demographic do not regret buying into an HOA and would do it again. The percentages of respondents who “do not regret, but would avoid next time”, “regret their HOA but might consider again” or “regret their HOA and would avoid next time” are also in the post.
To avoid joining the group that feels stress or regret, be sure you understand what you’re getting into (before you sign anything!) and choose an HOA that fully aligns with your needs. While the CC&Rs can change in the future using the amendment process set forth therein, but it is a high bar and you will have notice of the proposed change.
Verify what you’re paying for (and what you’re not). Every HOA will vary in terms of the fees that you’ll have to pay as well as what those fees actually cover. For instance, some associations will cover utilities like water and trash collection as part of your monthly fees, while others won’t. If there’s a cost you’re expecting to be covered, review the breakdown of what is covered to be sure.
Data (collected by the researcher noted in the post) on active-adult communities shows that HOA costs in 55+ communities typically range from $200 to $700 per month – on top of the mortgage payment. Things that might make the HOA dues more expensive are listed in the post.
And in addition to the monthly fees, you’ll most likely need to budget for a one-time “capital contribution fee” or “transfer fee.” This is paid at closing and what it covers or its purpose should be identified to you prior to that. The typical range for such fees is noted in the post.
Another cost to watch out for is special assessments, which are one-time costs that the HOA can charge for projects that exceed its current budget. These are not usually predictable and can (mostly) be avoided by proper management and planning. So what should you do? See the post.
Find out whether your heirs could be forced to sell. Never thought about that, did you? While HOAs set their own rules (subject to state or federal laws), one law that they all must abide by is the “80/20 rule” established by the Housing for Older Persons Act of 1995. In order that adult communities can have age restrictions (i.e., 55+) without violating fair housing laws, at least 80% of homes must have at least one occupant who is age 55 or older. So there’s leeway if you plan to have your child or grandchild live with you or if you’ll have a live-in caregiver. But the picture might change when your heirs eventually inherit the home.
One example is playing out now in Florida. See the post for details. Also see our posts of Wed. Aug. 5, 2026, here and here. In July, that community approved a special assessment to finance the litigation (the amount is in our Aug. 5 posts and might blow your mind). As of September, she was thought to still be living in the inherited home.
So while there are circumstances where a beneficiary isn’t allowed to live in a home they inherit in a 55+ community, there still might be a financial benefit since they can profit from the home sale. But the timing of that sale might not be great for the heirs. See the post for more on that.
If you are considering buying in a 55+ community, ask up front what happens to the home if it passes to someone under age 55.
Look beyond the brochures. While one of the main draws of 55+ communities is living among neighbors who are your peers in age, the communities are not homogenous or interchangeable. They can vary widely in terms of rules, costs and benefits, and a careful reading of the regulations and financials is a must.
TAKEAWAY: Know what you want to be able to do in your potential future home – and what rules or restrictions are in place that might touch on your wants. Consult a community association lawyer before you sign on the dotted line.