Below is a review of the posts on Facebook and LinkedIn from the past week. You can check out the full posts by clicking on the links.
NOTE: remember that we now post every other day.

The posts on Sunday 11/01/2026, here and here, noted that HOA opens clubhouse to secular groups + closes door on Bible study = legal action. Because even though prohibiting all religious group meetings seems uniform, it still is (or could be) discriminatory under the FHA.
Imagine living in a community where residents are encouraged to gather in the neighborhood clubhouse for group activities, games, hobbies, and other events, but are told they cannot gather there for one other reason: their meeting is religious. That’s exactly the situation in Illinois (but it could be anywhere.
Carillon North Homeowners Association promotes its clubhouse as a central gathering place where residents and their guests can meet and participate in various activities. Residents are encouraged to form groups and clubs to meet with like-minded residents in a variety of rooms around the clubhouse. In 2023, a Bible study group began meeting every Wednesday morning in the clubhouse. They would read and discuss Scripture, share prayer requests, and pray together. That was not an unauthorized use of the clubhouse. The group leader sought permission before the Bible study began meeting in the clubhouse and completed the HOA’s required reservation form each year to reserve the space. For more than two years, the Bible study met regularly with the HOA’s knowledge and approval. Then, in August 2026, the HOA abruptly changed course.
After the August 12th Bible study, HOA management explained that other residents wanted to use a clubhouse room for an annual Catholic Mass, but the HOA did not want to allow it. They were concerned that allowing the Bible study to continue meeting in the clubhouse could be used to challenge any decision prohibiting the Catholic Mass. So the HOA decided to ban all religious groups from using the clubhouse (but still allow non-religious, secular groups). The Bible group leader was then informed by the HOA’s president of the Board’s decision. The Bible study has not met there since, and the gathering has been removed from the community activities calendar. But the clubhouse remains available for secular activities.
A legal group then sent a letter to the HOA informing it that prohibiting religious groups from using its clubhouse, including weekly Bible study, violates federal law. The statute they cite, and its relevant language, is detailed in the post. They also cite a federal appellate court decision (which is linked in the post).
These facts present a scenario that is not just whether the HOA treats one religion better than another. First, the HOA’s ban on religious groups using its clubhouse is discriminatory on its face. Is that remedied by its application to all religious groups? See the post as to the real issue under the FHA (and another federal appellate decision that is linked there).
The statute is also informed by federal guidance that is fairly straightforward. The US Department of Justice (linked in the post) has explained that equal access to housing benefits means that someone cannot, “for example, be excluded from reserving a common room for a prayer meeting when that room may be reserved for comparable secular uses.”
This was not the first time the legal group stepped in to represent the rights of HOA residents under the FHA. In 1995, it settled a federal lawsuit in Virginia. The post has a ink to that and more details about it.
The letter sent to Carillon demands that it cease discriminating on the basis of religion and provide written assurances that the resident may again reserve and use the clubhouse for Bible study. And if the HOA refuses? See the post.
TAKEAWAY: Often community associations think that treating all similar groups the same makes that treatment legal; but when the treatment differs from that afforded other groups and there is a protected characteristic – here religion or religious beliefs – that distinguishes the groups, the treatment is probably illegal. Talk to a community association lawyer before enacting such a prohibition.
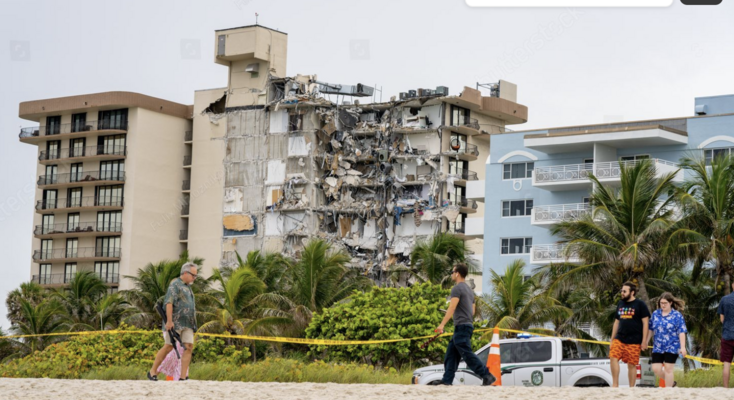
The posts on Tuesday 11/3/2026, here and here, explained that if you live in a condominium, this is probably one reason your dues or assessments will increase in 2027.
You should know from our posts on Sunday Aug. 9, 2026, here and here, Monday Aug. 3, 2026, here and here, Thursday May 21, 2026, here and here, and Friday April 3, 2026, here and here, that beginning January 4, 2027, mortgage giant Fannie Mae will require condo associations to set aside 15% of their budgets for reserves, an increase from the prior/current 10%. Associations that fail to meet the requirement could end up with units that are harder to finance – and therefore harder to sell. There is a bit of wiggle room: an association can obtain a qualifying reserve study instead of budgeting the prescribed 15%.
This new regulation affects buyers and sellers because lenders must comply. And if a condo doesn’t meet Fannie Mae’s requirements? See the post for the possibilities and effects.
For current condo residents, the reserve increase comes on top of rising costs throughout building budgets, including insurance and utilities. But ignoring the higher reserve allocation may not be smart. And the funds must come from somewhere – leading to the situation discussed in the post.
Boards do have another option: get a qualifying reserve study instead of automatically budgeting the prescribed 15%. What the reserve study does is in the post. But a reserve study does not necessarily save money for the association for the reasons noted in the post. And that would make the 15% reserve allocation less costly.
So now condo associations face dual swords: budget the 15% reserve which will probably result in increased assessments or don’t budget for it and potential buyers may have fewer and more expensive financing options. Or get a reserve study, which might peg the actual capital needs as equal to or exceeding the 15% reserve requirement. None of those options are especially attractive. Many in the industry – representing buyers, associations and lenders – are hoping that Fannie Mae will change course (as noted in some of our posts referenced above). Why are lenders also pushing back? See the post.
TAKEAWAY: The hurt is already being felt across the nation as condo associations put out 2027 budgets with increased assessments and owners must decide if they can afford the new amount or must move (voluntarily or otherwise).
The posts on Thursday 11/5/2026, here and here, gave us 12 reasons not to leave your house to your children when you die.
Planning for retirement, especially if you want to retire early, could and should also include nailing down your estate plans. You may be thinking about what to do with your home after you’re gone and might think it’s a good idea to leave it to your kids. But before you put that in your will or trust, here are a few reasons why you may not want to bequeath your home to your children.
1. There may be tax implications. This might be the biggest issue.Inherited property is typically valued at its fair market value on the date of death, which means your heirs aren’t taxed on the home’s appreciation during your lifetime. But gifting the home to them while you’re alive triggers a carryover basis. The potentially large tax implications here mean you need to talk to a tax or estate planning attorney.
2. There’s potential for sibling squabbles. The kids may agree on everything now, with you around, but that may not be the situation after you die. Then they may disagree on issues related to your home. One may want to keep the house, while the others want to sell it. Will that one child be able to buy out the siblings?
The solution if you decide to leave your home to your children, is to clearly spell out what should happen to your home after your death so there’s no squabbling. For example, is it to be sold and the net proceeds divided among them? If one can buy out the other, how is the sale price to be determined? And what happens if more than one child wants the house?
3. It locks up equity. Your home is likely to be your most valuable asset, but that also means there’s quite a bit of cash locked up in it. You need to keep that in mind when doing your estate planning – and when preparing for retirement. Some reasons you may want to sell the house (instead of leaving it to the kids) are in the post.
4. You haven’t paid off your mortgage. Do you expect the kids to move into the home after you die? If so, how will your kids will pay the mortgage? Some ideas are in the post.
5. Your kids don’t want it. You may want to leave your home to your kids, but what if they don’t want it? There are other options including the things in the post.
6. It’s (probably) cheaper to sell it to them now. Housing prices remain high, and many young people are struggling to enter the housing market. Think about selling your home to your kids now. Who would live there and pay the bills is discussed in the post. You could sell it to them, remain living there, and pay them rent. But this is another situation where you need to consult a tax attorney as to the implications for any type of sale.
7. Your kids have financial problems – Millions of Americans struggle with financial issues, and your kids could be in that group. If so, there could be an effect as to your kids’ creditors. So you need to do the things noted in the post.
8. You’re behind on property taxes. That becomes the problem of your kids if you leave the house to them. Do you want to d that to them?
9. You’re playing favorites – You may think one of your kids may need your home more than your other children, for whatever reason. It’s usually best to avoid playing favorites. (F you do want to leave the house to just one of the children, then consider the other action noted in the post. Or think about the alternative also in the post.
10. They can’t care for your home – Othe bills keep piling up. Not just taxes, but utilities, maintenance, and repairs. Again, how will they pay for those things? Plan for that.
11. They’ll be too sentimental – there might be sentimental reasons you want to leave the house to the kids, but that could also make it harder for them to make decisions about it. Necessary decisions. So you need to help by doing the things in the post.
12. You’re on Medicaid – Medicaid is an excellent option if you can’t afford medical care on Medicare alone. But there are issues with Medicaid if you pass away and your kids have to deal with your estate, including your home. What that means, and a bit about how it works, is in the post. So plan for this ahead of time by doing the things in the post.
Bottom line – Make sure you understand all of the financial and emotional effects of leaving your home to your children.
TAKEAWAY: It’s important to discuss your individual situation – current and future financial status as well as your preferred asset distribution after death – with an estate planning attorney before just deciding to leave your house to the kids.
The posts on Saturday 11/7/2026, here and here, told us how a backyard fence dispute cost an HOA $200K.
Good fences do not always make good neighbors as one neighborhood discovered last year. A drawn-out court battle resulted in each of the nearly 100 property owners in the neighborhood being on the hook for $1,350 to settle a five-year-long dispute over one household’s desire to put up a fence. The payments were the result of a federal court ruling that the Nazcr Trac Property Owner’s Association (NTPOA) board improperly denied the Newman family’s request to construct a backyard fence. The result, in addition to the monetary impact, was a community divided and pointing fingers. Let’s take a deeper dive
The dispute began in 2019 when the Newmans asked if they could build a backyard fence so that their five children, all of whom have been diagnosed with Autism Spectrum Disorder, could play outside safely. It had been determined by the children’s doctors and caregivers that a fence would be the best option (for the reason noted in the post). Months later they found out (secondhand, by mentioning the matter to a neighbor who told them) the HOA denied the request based on a restrictive covenant that states “No fences of any kind shall be allowed.” The board members also based their decision on past fence denials. The Newmans then sent in a formal request for accommodation and included in the packet the doctor’s notes and a joint memo from US DOJ and HUD relative to FHA obligations. The HOA did not respond to the Newmans. More than 2 months later the HOA sent a letter to all members that included a note that the board must abide by the fence prohibition in the covenants. AUTHOR’S NOTE: does anyone hear alarm bells sounding?
A disability rights group advised the Newmans to get a lawyer and they filed suit in 2021 against the HOA and the then-President. The following year, a federal court judge granted them a preliminary injunction under the Fair Housing Act (FHA) and they built their fence. But that’s not the end …
About 2 years later, in August 2024, a settlement was reached which ordered the NTPOA to pay the Newmans $200,000 (probably on account of attorneys’ fees incurred by the Newmans). This would be a general common expense borne by all members of the HOA (except the Newmans), which means that it was not covered by HOA insurance. What Mrs. Newman said about the settlement is in the post.
And the feeling of owners? See the post for that too.
TAKEAWAY: Board members must know not only the governing documents, but what local, state or federal statute (or rule or ordinance) may require them to deviate from the association’s restrictions. It is best to consult a community association lawyer before dipping a toe in a pool that might end up being very costly to the association and its members.